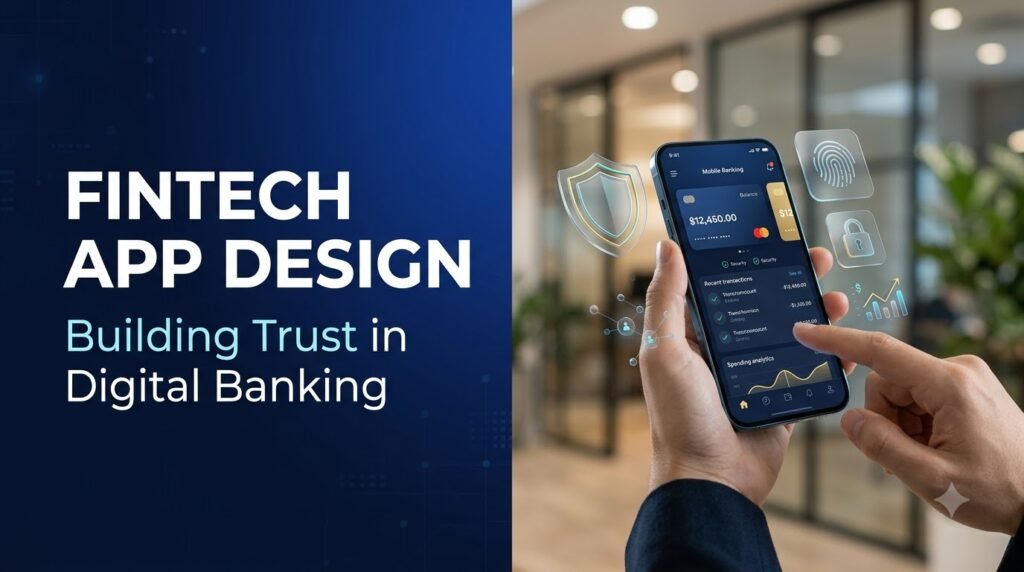
Fintech applications have transformed how people manage their finances, transfer money, monitor spending and interact with financial institutions. Customers increasingly expect banking services to be available through intuitive mobile applications that provide convenience, clear information and confidence when handling sensitive financial transactions. For fintech startups, digital banks and established financial institutions, meeting these expectations requires more than developing an application with an attractive interface.
Effective Fintech app design brings together usability, accessibility, transparency and security-conscious interactions to create a dependable digital experience. Every screen, notification and transaction flow influences how customers perceive a financial service. When users can understand their balances, complete payments confidently and find assistance when something goes wrong, they are more likely to feel comfortable using the application.
At the same time, strong design must be supported by reliable engineering. Mobile banking app development combines thoughtful user experience design with secure architecture, appropriate integrations and dependable performance. Businesses serving customers in the UK, UAE, Australia and other international markets must also consider local customer expectations, accessibility needs and applicable regulatory requirements.
This article explores how thoughtful design can strengthen customer confidence, improve usability and help financial businesses create more effective digital banking experiences.
Why User Trust Matters in Digital Banking
Trust is fundamental to financial services because customers are not simply browsing information or purchasing everyday products. They are accessing sensitive personal data, managing their money and authorising transactions that can have immediate financial consequences.
A confusing payment screen, unexplained fee or unclear transaction status can create unnecessary anxiety. Even when an application functions correctly, poor communication may make customers question whether their money has been transferred successfully or whether their account information is protected.
Strong Customer trust in digital banking influences several aspects of the customer journey:
-
Adoption: Customers need confidence in a service before moving important financial activities to a digital platform.
-
Continued engagement: Consistent performance and understandable interactions encourage customers to keep using an application.
-
Transaction confidence: Clear payment details, confirmation screens and transaction records help users understand what they have authorised.
-
Customer satisfaction: Straightforward navigation and helpful support reduce avoidable frustration.
-
Perceived privacy: Transparent explanations of data collection, permissions and security measures help customers make informed decisions.
Trust is not established through branding alone. It develops through repeated experiences in which the application behaves predictably, communicates honestly and gives customers appropriate control over their financial activities.
How Fintech App Design Builds Customer Confidence
Create a Clear and Consistent Interface
Customers should not need to learn a different navigation pattern for every section of a banking application. A consistent interface makes it easier to locate account balances, transaction histories, payment options, settings and support resources.
Designers can improve clarity by using familiar navigation patterns, readable typography, consistent buttons and recognisable visual indicators. Important actions, such as confirming a transfer or freezing a card, should be easy to identify without overwhelming the screen with competing elements.
Visual hierarchy is particularly important in financial applications. Account balances, payment amounts, recipients and transaction statuses should receive appropriate prominence. Secondary information can remain accessible without distracting users from the task they are completing.
Good UI/UX design for fintech applications also accounts for different levels of financial and technical familiarity. Straightforward labels such as “Send money” or “View transactions” are generally more useful than internal banking terminology that customers may not understand.
Make Financial Information Easy to Understand
Financial information should be presented in a way that helps customers make informed decisions. An interface that displays numbers without sufficient context may technically provide the information users need while still leaving them uncertain about what those numbers mean.
Account dashboards should distinguish available balances from pending transactions or other relevant balance figures. Transaction histories should provide useful details, such as dates, merchant or recipient names, amounts and payment statuses.
When fees apply, the application should explain them before customers commit to a transaction wherever practicable. Transfer screens should clearly identify the recipient, amount and relevant charges, allowing users to review the details before confirming.
Spending summaries can also improve understanding by organising transactions into useful categories. These summaries should be clearly labelled and allow customers to inspect the underlying transactions rather than treating automated classifications as unquestionably accurate.
The objective is to make financial information understandable, not simply to display more of it.
Use Transparent Feedback and Notifications
Customers need to know what happens after they interact with a banking application. A button that appears to do nothing after a payment is submitted can create uncertainty and may lead users to repeat the action unnecessarily.
Well-designed feedback addresses this problem by communicating the current state of an activity. A payment interface might distinguish between a transaction that is processing, one that has completed and one that requires further action.
Notifications should provide useful context without exposing sensitive information unnecessarily. Security alerts, payment confirmations and account activity messages should explain what happened and indicate the appropriate next step when action is required.
Error messages deserve the same attention. Instead of displaying a generic failure notice, an application should explain the problem in accessible language and offer a practical resolution where possible.
Transparent communication helps customers understand the system without requiring them to guess what is happening behind the scenes.
Design for Accessibility and Inclusion
Accessible banking applications enable more people to manage their finances independently, including customers with visual, motor, hearing or cognitive accessibility needs.
Accessible design should include sufficient colour contrast, scalable text, clearly labelled controls, meaningful screen-reader descriptions and logical keyboard or assistive-technology navigation where applicable. Interactive elements should also be large enough to use comfortably, particularly on smaller mobile screens.
Language matters as well. Short sentences, descriptive labels and clearly explained financial terms help people with different levels of digital confidence understand important decisions.
Accessibility should be considered from the beginning of a project rather than added as a final adjustment. Testing with assistive technologies and users with different needs can reveal barriers that may not be apparent to the design team.
Inclusive design improves usability across the wider customer base, not only for people who rely on specific accessibility features.
Build Credibility Through Consistency
A professional, consistent experience helps customers understand what to expect from a financial application. Differences in terminology, unexpected changes in navigation and inconsistent transaction messages can make the service feel unreliable.
Consistency should extend across onboarding, account management, payment processing, notifications and customer support. If the application uses a particular term for a transaction status, the same terminology should appear throughout the relevant journey.
Trust also depends on setting realistic expectations. An application should not promise instant transfers if a transaction may take longer, nor should it imply that an account is fully protected simply because biometric login is enabled.
Reliable design communicates clearly about what the service can do, what it cannot do and what customers should expect next.
The Role of Mobile Banking App Development in Better Digital Experiences
Mobile banking app development involves much more than translating banking services into a mobile interface. It requires the coordination of user experience design, application architecture, transaction workflows, security controls and integrations with the systems that support financial operations.
The most useful features are those that solve real customer problems without adding unnecessary complexity.
Core capabilities may include:
-
Account management: Allow customers to review balances, access account details and manage relevant preferences.
-
Payments and money transfers: Provide clear recipient details, transaction reviews and appropriate confirmation steps.
-
Transaction histories: Make previous payments, deposits and other account activities easy to find and understand.
-
Card controls: Where supported, allow customers to manage card settings, report a lost card or temporarily freeze a card.
-
Notifications: Communicate relevant account activity, payment statuses and security events.
-
Account settings: Provide accessible options for privacy preferences, authentication, contact details and support.
The design of these features should reflect how customers actually use financial services. For example, someone checking a balance may need a quick overview, while someone transferring a large amount may benefit from a more detailed review screen.
Technical integration is equally important. Banking applications may need to communicate with banking infrastructure, payment providers, identity verification services and other third-party systems. Appropriate API integration can connect these components, but each connection requires careful consideration of permissions, data handling, error management and reliability.
Feature selection should be based on customer needs, business objectives, technical feasibility and applicable regulations. Adding every available feature can make an application harder to navigate. A focused set of dependable capabilities often provides a better starting point than an overloaded dashboard.
Essential Security Features That Support User Trust
Customers need to feel confident that their financial information and transactions are handled responsibly. Good design can make security measures easier to understand and use, but the underlying protection must come from sound engineering and operational controls.
Biometric Authentication and Multi-Factor Authentication
Biometric authentication, such as fingerprint or facial recognition where supported, can provide a convenient way to verify a user’s identity. Its implementation should account for device capabilities, fallback methods and the security of the underlying authentication process.
Multi-factor authentication (MFA) adds another layer of verification when appropriate. Depending on the service and risk, this may involve an authenticator application, a trusted device or another supported verification method.
The interface should explain why additional verification is required and guide users through the process without revealing sensitive security details. Recovery options must also be designed carefully so that users can regain legitimate access without creating an easy route for unauthorised access.
Secure Sessions and Account Recovery
Login and account recovery are particularly important because customers may be using unfamiliar devices, changing phones or dealing with a suspected security incident.
Applications should communicate session timeouts clearly, protect sensitive screens appropriately and provide understandable steps when authentication fails. Account recovery should explain what information is needed, how verification works and what happens after a request is submitted.
Security measures should be proportionate to the risk. Unnecessary interruptions can frustrate legitimate users, while inadequate verification can expose accounts to misuse.
Transaction Confirmations and Fraud Alerts
Before customers authorise important transactions, the application should make relevant details easy to review. Depending on the transaction, these may include the recipient, amount, destination and applicable charges.
Fraud warnings should be specific enough to help customers act. Rather than relying entirely on alarming language, a warning can explain the concern and provide a safe next step, such as reviewing the recipient details or contacting the institution through a verified support channel.
Privacy Controls and Financial Data Protection
Customers should understand what personal information an application collects, why it is needed and how relevant permissions can be managed. Consent screens should use clear language and avoid making optional data use appear compulsory.
Strong Mobile app security also depends on secure coding, appropriate encryption, access controls, protected API communications, backend safeguards, vulnerability testing, monitoring and incident response. Security responsibilities must extend beyond the visible interface.
Financial businesses should assess applicable privacy, consumer protection and financial-services requirements in each market they serve. Design decisions can support compliance, but neither a polished interface nor a particular authentication feature guarantees that an application meets every legal or regulatory obligation.
Reducing Friction in the Digital Banking Journey
Customers can lose confidence when routine activities require unnecessary effort. A lengthy registration process, confusing identity checks or an unclear payment failure can turn a convenient digital service into a frustrating experience.
The answer is not to remove every verification step. Financial services may need to collect information and perform checks to meet legitimate security, fraud-prevention and regulatory requirements. Instead, design should make necessary steps easier to understand and complete.
Consider these practical improvements:
-
Simplify onboarding: Request information in a logical sequence and explain why important details are needed.
-
Show progress: Use progress indicators so customers understand how many steps remain.
-
Explain verification requirements: Provide clear instructions before requesting documents, permissions or additional checks.
-
Improve payment forms: Group related fields together, label them clearly and allow users to review important details before submission.
-
Clarify transaction statuses: Explain whether a payment is processing, completed, pending or unsuccessful.
-
Support error recovery: Offer relevant next steps for failed logins, declined transactions and forgotten passwords.
Usability testing can identify where customers hesitate, make repeated mistakes or abandon a task. Design teams can then investigate whether the issue stems from unclear language, unnecessary steps, technical performance or a legitimate verification requirement.
A strong Mobile banking user experience reduces avoidable friction while preserving necessary protections. The goal is to make important financial activities straightforward, not to make them careless.
Personalisation and Smarter Digital Banking Experiences
Personalisation can make digital banking more relevant by presenting useful information according to customers’ needs and preferences. However, it should improve control and clarity rather than introduce unnecessary complexity.
For example, customers may benefit from customisable dashboards that prioritise their preferred accounts, recent transactions or frequently used payment options. Spending categories and financial summaries can help users understand their activity, while optional budgeting tools can support everyday money management.
Relevant alerts can also improve the experience. A customer may choose to receive notifications about certain transactions, account thresholds or upcoming payments, where those features are available.
Privacy should remain central to these decisions. Financial applications handle particularly sensitive information, so personalisation should be transparent, proportionate and consistent with appropriate data practices.
Businesses should explain how relevant data is used, provide meaningful controls over notification preferences and avoid collecting information without a clear purpose. Automated insights should also distinguish estimates from confirmed facts and allow users to question or correct inaccurate categorisation.
Well-designed Personalised banking experiences help customers find relevant information more easily while preserving their ability to decide how they interact with the service.
Common Fintech App Design Mistakes to Avoid
Even technically capable applications can struggle when their interfaces make financial tasks unnecessarily difficult. Several common mistakes can undermine customer confidence.
Prioritising appearance over usability: Visually impressive screens are not enough if customers cannot find essential functions. Design decisions should be tested against real tasks.
Hiding fees or important terms: Customers should have access to relevant costs and conditions before making a financial commitment. Unclear disclosures can damage trust.
Using confusing terminology: Internal banking language may be familiar to developers but unfamiliar to customers. Use plain English and explain unavoidable technical terms.
Overloading dashboards: Displaying too many charts, alerts and shortcuts can make important information harder to find. Prioritise the most useful content and provide access to secondary details when needed.
Making security messages unclear: Vague or unnecessarily alarming warnings may cause users to ignore legitimate alerts or make poor decisions. Explain the concern and the appropriate response.
Ignoring accessibility: Small controls, poor contrast and inaccessible forms can prevent customers from completing important tasks independently.
Providing vague error messages: Telling customers that something went wrong without explaining what to do next creates frustration and repeat attempts.
Collecting unnecessary personal information: Excessive data requests can undermine confidence and increase the burden of protecting sensitive information.
Neglecting testing and maintenance: Unresolved defects, inconsistent behaviour and deteriorating performance can erode trust over time.
Avoiding these mistakes requires collaboration between designers, developers, security specialists, product teams and customer support staff. Design quality is an ongoing responsibility rather than a one-time deliverable.
How to Choose the Right Fintech App Development Partner
Choosing a technology partner is an important decision for fintech startups, digital banks and established financial institutions. The right partner should understand that financial applications require careful coordination between customer experience, software architecture, data protection and operational reliability.
When evaluating Fintech app development providers, consider the following areas.
UI/UX design and research: Ask how the team gathers user requirements, maps customer journeys, creates prototypes and tests designs with representative users. A clear design process helps identify usability problems before they become expensive development issues.
Engineering and integration capabilities: Assess the team’s ability to build maintainable applications, work with APIs and integrate appropriate third-party services. Ask how integration failures, data inconsistencies and service interruptions will be handled.
Security-focused development: Discuss secure coding practices, access controls, testing procedures, vulnerability management and incident handling. The partner should explain its approach clearly rather than relying on broad promises about security.
Privacy and regulatory awareness: Requirements differ between jurisdictions and business models. A suitable partner should be able to discuss the technical implications of relevant requirements and work with the client’s legal, compliance and security specialists where necessary.
Testing and quality assurance: Understand how the team tests different devices, operating systems, network conditions, authentication flows and transaction scenarios. Accessibility and usability testing should be part of the process.
Communication and documentation: Clear project milestones, technical documentation, ownership arrangements and transparent reporting make it easier to manage delivery and future changes.
Ongoing support: Ask how defects, updates, performance issues and security improvements will be managed after launch. Dependable Fintech app maintenance and support can help keep the application aligned with changing user needs and technical requirements.
Ambient Infotech offers web and mobile application development alongside UI/UX design and software development services. Businesses considering a financial application can evaluate its capabilities against their project scope, integration needs, security expectations and support requirements.
The most appropriate partner is one that communicates limitations honestly, documents its work and can demonstrate a practical approach to building and maintaining reliable applications. For complex financial products, clearly defined responsibilities between the technology provider and the client’s specialist security and compliance teams are particularly important.
Measuring the Success of Fintech App Design
A successful design should be evaluated through observable improvements in usability, customer confidence and application performance. Visual appeal alone cannot establish whether a banking experience is effective.
Teams can combine quantitative metrics with customer feedback to understand how well an application supports its intended tasks.
| Metric | What it helps measure |
|---|---|
| Onboarding completion rate | Whether users can complete registration and setup |
| Task completion rate | Whether customers can perform important actions successfully |
| Payment and transfer failure rate | How frequently transactions fail, with causes investigated separately |
| Usability-related support requests | Where customers encounter confusion or repeated difficulties |
| Customer satisfaction and feedback | How users perceive the overall experience |
| Accessibility testing outcomes | Whether the interface supports users with different needs |
| App stability and performance | Whether the application remains responsive and dependable |
| Retention and feature adoption | Whether customers continue using the service and discover relevant features |
Metrics must be interpreted carefully. A low onboarding completion rate, for example, could indicate confusing design, technical problems, unsuitable acquisition traffic or necessary verification steps that customers cannot complete. The number alone does not reveal the cause.
Similarly, a high transaction completion rate does not automatically prove that customers understand the fees or feel confident about the process.
Usability testing, customer interviews, support-ticket analysis and carefully designed experiments can help teams identify the reasons behind observed patterns. Financial applications should also use privacy-conscious analytics and collect only the information needed for legitimate evaluation.
Regular reviews help teams prioritise improvements according to customer impact, business requirements, security considerations and technical effort.
The Future of Trust-Centred Digital Banking Design
Digital banking design continues to evolve as customer expectations, device capabilities and financial technology change. The most useful developments are those that make financial services more understandable, accessible and dependable.
More inclusive interfaces can improve access through clearer language, better assistive-technology support and adaptable presentation. These capabilities should be evaluated with users who have different needs rather than relying on assumptions about accessibility.
Responsible AI-assisted insights may help customers organise spending information or identify useful patterns. Such features should explain their limitations, avoid presenting uncertain outputs as facts and give users appropriate control over how insights are generated and used.
Improved fraud-warning experiences can help customers recognise potentially risky activity and understand what action to take. Warnings need to be timely, clear and designed to avoid unnecessary alarm.
Seamless but secure authentication can reduce avoidable interruptions while retaining appropriate verification. The best approach depends on the transaction, threat model, device capabilities and relevant requirements.
Greater transparency around data use can help customers understand how their information supports the service. Clear privacy controls and understandable consent choices will remain important as applications introduce more personalised features.
Consistent mobile and web experiences can reduce confusion for customers who move between devices. Shared terminology, predictable navigation and reliable synchronisation can help users maintain continuity across channels.
These developments should not be adopted simply because they are new. Each feature should be evaluated for its customer benefit, accessibility, fairness, privacy implications, security and operational cost.
Conclusion
Trust-centred Fintech app design requires a careful balance of intuitive navigation, transparent financial information, accessible interactions, reliable performance and clear security communication. Customers should be able to understand their accounts, complete important transactions and resolve problems without unnecessary confusion.
Effective Mobile banking app development turns these principles into working digital services through thoughtful user journeys, maintainable engineering, appropriate integrations and ongoing testing. Security must be built into the underlying systems, while the interface helps customers understand and use protective measures correctly.
For financial businesses operating in the UK, UAE, Australia and other international markets, the strongest approach begins with customer needs and considers the requirements of each market throughout the development process.
Ambient Infotech can be considered by businesses exploring mobile application development, UI/UX design and custom software solutions. Evaluating the provider’s capabilities, delivery approach and ongoing support against the specific needs of a financial project is an important step towards choosing the right technology partner.
Ultimately, a trustworthy digital banking experience is built through consistent decisions that respect customers’ time, privacy, accessibility needs and financial security.